


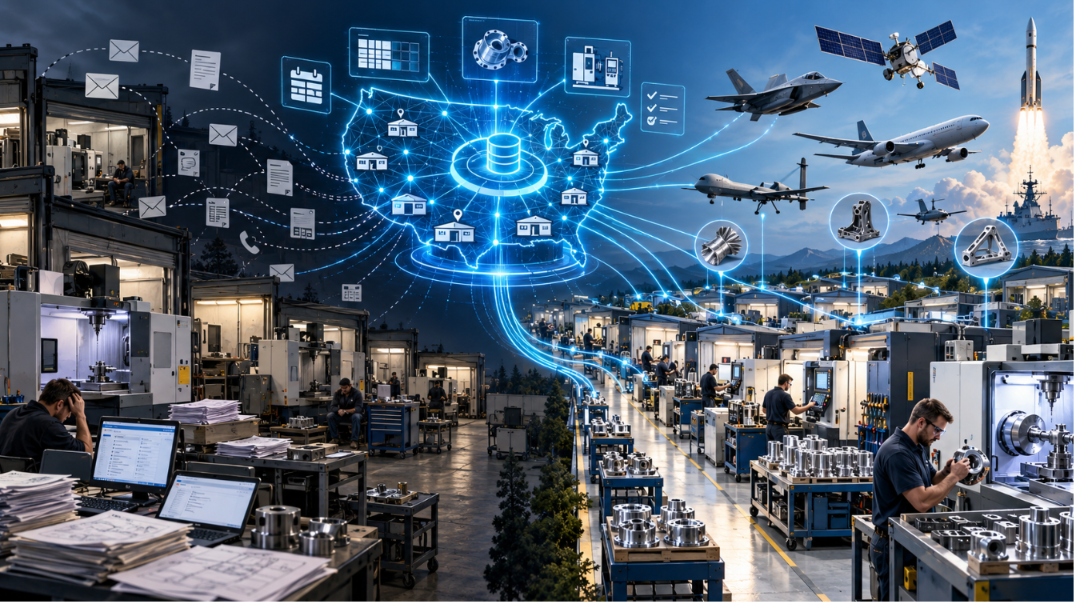
Dan runs a machine shop in Sterling Heights, MI, equipped with ITAR-registered four- and five-axis mills; exactly the kind of shop every report on the defense industrial base says our country is short of. Yet, until last year, he wasn’t winning defense work. Today, his machines cut parts for satellite startups, space companies, and some of the fastest-growing defense technology firms in the U.S.
Nothing on his factory floor actually changed; no new machines, software, or certifications were added. What changed is that work finally started reaching him because a new coordination layer began handling the finding, quoting, and qualifying processes that a shop his size simply doesn’t have the manpower to do.
The U.S. has 16,876 machine shops. A staggering 83% of them operate with fewer than 20 employees, and the average machine across these facilities runs about a quarter of the time. The capacity certainly exists, but it remains heavily fragmented. Crucial tasks like quoting, scheduling, revisions, and qualifications happen inefficiently via phone and email. While primes and defense startups coordinate their own direct suppliers, no entity manages the “supplier tail”; the thousands of independent shops that actually produce the parts. I constantly see companies win a $200M production order only to discover their primary bottleneck is a supplier base they cannot find, qualify, or keep.
Andreessen Horowitz accurately diagnosed this issue in their case for an American manufacturing asset class, noting that small shops operate as disconnected businesses rather than one unified system. Technologies like smart sensors, industrial IoT, digital twins, physics-informed AI, and Hadrian’s Opus scheduling systems make individual factories significantly better, and our country needs every one of them. The real problem sits between these facilities: in week-long quoting processes, late revisions, and repetitive customer qualifications. You can instrument every spindle in Ohio, but the drawing still sits in an inbox waiting on a quote nobody has time to write.
Before new coordination layer existed, a request for quote reached Dan the way it reaches most shops: a zip file of forty drawings, and outdated military specifications from 2009. He read all forty to find the three his machines could make and wrote the quote at night, because during the day he is also the salesperson, the compliance officer and the one running the five-axis. Shops land about a third of what they quote, so most of those nights were for nothing. If he won, the paperwork started: portal, NDA, supplier survey, ITAR letter, cybersecurity questionnaire, first-article package, all of it repeated for the next customer in a different format.
Softer friction costs our industry even more. Missed portal messages regarding bore tolerances, revisions arriving after material is cut, and uncommunicated supply chain delays frequently idle machines. This structural inefficiency is exactly how parts end up in Shenzhen. While vertically integrated, state-backed Chinese factories answer quotes in two hours, American shops struggle with coordination. Over a decade, small businesses in the U.S. defense industrial base plummeted by more than 40%, while Chinese suppliers in the Pentagon’s supply chain grew by 420%.
Acquisition adds to this without intending to. The government buys program by program, so nobody in the department owns a process family across programs, and the shop that could serve six of them is invisible to all six. The certainty Congress gives a program through multiyear procurement reaches the prime and mostly stops there. Compliance written for primes flows down to a 15-person shop with little adjustment. Every rule has a reason (configuration control, security), but sum of them lands on the small business owner.
Consolidation into single megafactories is not the American answer; our 17,000 independent shops provide necessary redundancy. Artificial intelligence performs its most vital work one layer above the factory floor by aggregating historical data from purchase orders and inspection reports to build capability profiles based on actual outcomes. AI instantly matches drawings against these shop profiles, checking historical tolerances, verifying stock, and calculating pricing. Dan’s quoting shrinks from a long night to twenty minutes. Networks utilizing this approach ensure American shops receive work because they consistently deliver. Defense startups like Anduril already run private versions of this idea, sourcing components from broad commercial supply chains to scale when demand arrives. However, a shop owner cannot plan a business based on a single customer’s forecast; they need an aggregate picture of demand to confidently invest in new equipment.
The fix is spread across three groups.
Industry
We must treat the supplier tail not as a disposable list of one-off vendors, but as a unified, strategic network. Primes need to share verifiable demand, process family, volume ranges, and delivery cadence, at a level that allows a small business owner to actually plan their capital investments. While megafactories are appropriate for final assembly and high-volume lines, the dynamic, high-revision long tail of machined parts belongs in a responsive, distributed network. Industry leaders must answer quotes promptly, route work where it fits, and compensate shops for design-for-manufacturing input.
Acquisition
Program managers and contracting officers must shift their mindset to view sub-tier suppliers as a holistic capacity resource. When a prime wins a funded lot, process-family forecasts to qualified sub-tier suppliers should be a mandatory deliverable under the award. Furthermore, we need shared onboarding baselines; if a shop is vetted for one program, that qualification must count on the next, much like how primes collectively govern the National Aerospace and Defense Contractors Accreditation Program (NADCAP). At the enterprise level, the Industrial Base Policy office holds the unique vantage point to aggregate and publish sub-tier demand across portfolios, which is the highest-leverage action it could take.
Congress
The standard reflex of imposing set-aside targets misses the mark entirely, as it measures prime contracts while ignoring the independent shops sitting two tiers down. In the next NDAA, when Congress grants multiyear procurement authority, it must attach a flow-down mandate for rolling demand forecasts, placing the obligation on the prime so the shop simply receives the forecast. Congress should also fund retainer pilots for sub-tier shops out of multiyear munitions lines to shield them from the stop-and-go friction of continuing resolutions. Finally, we cannot keep crushing 15-person shops under new compliance regimes; the security intent of CMMC is valid, but the execution fundamentally misallocates the regulatory burden.
We are staring at a massive asset class where returns are dictated strictly by utilization. Injecting capital into factory-floor tools is insufficient without pricing and funding the coordination layer that routes the right work to the right shop. The first companies and procurement offices to successfully synchronize these 17,000 independent shops into a unified network will secure an insurmountable competitive advantage.
Stephen Rodriguez is an operating partner at DCVC and an investor in more than 25 companies in the defense industrial, critical minerals, and global supply chain sectors. He is a life member of the Council on Foreign Relations and a commission director at the Atlantic Council.
Adar Hay is co-founder and chief executive of Jiga, which coordinates manufacturing for aerospace, defense and industrial programs across a network of U.S. suppliers.